Tuesday, June 13, 2006

Step Right Up. Get Your Degree! We Offer 30 Year Loans Too!

Having a degree is supposed to increase your earnings through your lifetime by one million dollars. Not bad right? Well, not if you graduate with a six digit loan. In an article on USAToday.com, a graduate student, Palazzolo, graduates from Rutger's University with $116,000 in loans. Absurd! Another example taken from the article:
Angela Schneider, 26, graduated last year from Simmons College in Boston with a master's degree in social work and $118,000 in student loans. To make her monthly payments of $800, Schneider has taken on a part-time job providing in-school therapy in addition to her full-time position as a medical social worker. She's living on a tight budget that allows her $70 a month for entertainment.
Granted these folks are graduating with a Masters, but still. $70 monthly entertainment budget?! For how long? And finally:
Routsong decided to return to school to get her master's degree as a nurse practitioner. She looked into nursing programs at several community colleges. All had two- to three-year waiting lists. She entered an accelerated program at the University of San Diego, a private school, that will enable her to get a master's in three years. She's borrowed $65,000 and expects her loans to top $165,000 by the time she graduates. Her student debt, she says, occupies a place in the recesses of her mind.
That last line just gets me. It occupies a place in the recesses of her mind? Like an afterthought, when it should be one of the main issues BEFORE deciding what to pursue. If it doesn't make sense, like in this case, to me it doesn't, then I think you have to formulate another game plan. If this is really what she wants to do, then there are others ways to do it. I'm not saying it's easy to find other ways, like getting your company to help pay for some of the expenses, but it's possible. USAToday.com Blogs has some interesting comments...One day, I hope my blog has this much reader interest! Hah. Bottomline: "Go to the best school (with the best program of study you're interested in) that you can AFFORD."

Monday, June 12, 2006

Housekeeping Done

I mentioned housekeeping about a week ago, well, unfortunately, some blogs are being removed. It's sad to see these blogs removed, but if the authors are still reading, I wish them the best! If you come back, please let me know.

Waterfront Property From $100/Month In Hawaii and Get Your First Month Free!

It's a "studio." Just need to add your own bathroom, kitchen, and other living necessities...oh and no windows from your "room." :) Okay, I understand people want to store stuff. They are willing to pay to store extra stuff (Stuff they will probably never see or use in their lifetime, in my opinion). As Everybody Loves Your Money points out, "Paying to Store C-R-A-P." Well this one takes the cake, a beautiful location, over looking the ocean, close to the beach is becoming a, you guessed it, self-storage location! Check it out. This is not the only one to take prime real estate in Hawaii btw, there's one close to a major mall and concert hall opening up, there's one by the University, there's one right smack in the middle of downtown. I need to open a self-storage location up! Talk about passive income.

My Home: If You Believed Housing Prices Would Come Down...What Would You Do?

If you believed that housing prices will come down within a couple years, but you found a pretty good deal on a house at the right price, would you go for it? Or would you wait? I've heard lots of arguments. It's an investment, and you can't time the market. There's only so much land, prices will always go up. And many more... Or, would you hold out until a specific date? In my situation, summer 2007. After thinking about it, I've come to the conclusion that sometimes that saying opportunity comes once in a lifetime leads me to make decisions that are not always in my best interest. The fact is opportunity is always there, you just have to find it. I'm going to hold out. I can accept my decision should housing prices go up, but I think I would have a harder time accepting if I bought and prices went down.

Tuesday, June 06, 2006

Gonna Do Some Housekeeping. Cleaning the Blogroll.

I'm planning on doing some blogroll housekeeping. I wish I could keep everyone on the list, but it is a little long. My plans are to remove blogs that have not been updated in the past month when I check them. I'll post blogs that have been removed. If you want to be added back on, just let me know.

Monday, June 05, 2006

My Home: Prepping My Credit Score

One of the first things you should do as you embark on the journey of buying a house is getting to know you're credit score. This will tell you if you are on track to get the best rates available. A score of 720 and above is considered to be in the upper tier, based on my meeting with the loan officer at my credit union, and you should have almost no problems getting the best rates with a score like that. I'm not sure if there are even better rates to be had if your score is, say, 800+, but it doesn't hurt. I'm know my Experian credit score is 762 right now, but I'm not sure about the other 2 credit agencies. My credit union told me that they take the 3 scores, and look at the middle score as the one they use to establish my loan. I'll have to work on that. In preparation, I've decided to limit my credit inquiries to only essentials. This means no more 0% credit cards for awhile. I'm also targetting January 07 as when I'll pay off a majority of my credit card debt, which is at 0% right now. One credit card has 0% set until midyear 07, so I won't pay off everything. My main goal is lower my debt to credit limit. Too high of a ration, hurts my credit score. So far, that's my only plans in place. I'm not sure if I'm going to be able to resist a two year 0% offer though!

Do You Know What To Do With Your Money When Retirement Comes?

All this talk about saving for retirement, but no one really talks about after you've saved your money, then what? Do you take out one big lump sum? Do you take out a couple percent? This article Know when to break the retirement investing rules, USAToday.com, has some specifics on what to do...First two are known, but the last one struck me as most interesting...First two being:
1: You'll need 60% to 80% of pre-retirement income to keep your current standard of living once you retire.
2: Tap regular accounts before tax-deferred ones in retirement.
Here's the last suggestion...
3: Withdraw 3% to 4% of your portfolio a year, then adjust upward for inflation.
I never really knew the specifics of how much to take out...A specific amount puts the other suggestions into perspective.

Friday, June 02, 2006

How Do I Grow My Net Worth Without Revealing My Income...

This is going to be tough...I don't want to reveal my income for various reasons, the biggest being the potential discovery of who I am by my work colleagues. I just posted my net worth, so I figured it be appropriate to discuss how I save...without revealing my income. - I live with my parents. Yes, in Hawaii, it is not uncommon to see many generations under one roof. It's just the style of living here. Thus my expenses are limited--gas, mobile phone service, cable, auto insurance, etc. I don't pay rent. I've offered... - I work from home, thus my gas and maintenance costs are very low. - I am pretty thrifty always looking for the best deals. However, I do go on an occasional splurge, as demonstrated this month. I restrict my splurge purchases, or try to anyway, to things that I've wanted for at least 6 months. I also buy things on sale if at all possible and practice the art of tease shopping. - I use my credit card for all purchases, rarely using cash. This saves me close to 1% on almost everything. - I eat out at places I find coupons or there are specials at. - I like to do "free" entertainment activites like fishing, going to the beach, taking my dog to the dog park... Some areas I need to work on: - My investment growth. - Eating out less. - Spending...who doesn't! So there you have it. How I save without revealing my income.

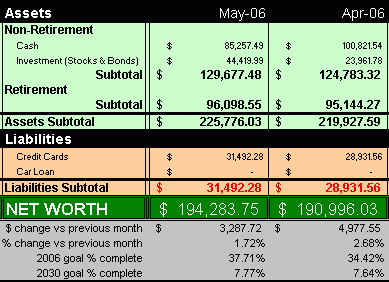
05.2006 Net Worth [+$3,287.72, +1.72%]

The theme of this month? Getting over my luxuries. Coming out positive is good, but considering the percentage, I'm way off target to hit my goal for the year. This month was a month of expenses: - Additional expenses for airfare. - A couple new toys, as detailed here. Including a new fishing reel which was not mentioned. - A fair amount of driving this month, meant more spent on gas. I also shifted a bunch of cash from my savings to my investment account. It's not invested yet, but will be soon. Read my posts on asset reallocation. June and July should be a good months. No unusual expenses expected, however, August is going to be bad.

Thursday, June 01, 2006

Your ID Is Stolen. That Sucks. Now What? 9.3 Million Victims.

Hope this never happens to anyone, but what if it does? How will you know? What do you look for? Who should I call if you think something is wrong? Tons of articles advising you on what if your credit is stolen telling you to call your credit card companies, credit bureaus, banks, etc. But what if you think you're just being too cautious? STOP. You can never be too cautious. Here are the steps I take to prevent my ID from being stolen: - I use the government's gift of a free annual credit report. And take the time to look through your entire history to make sure nothing seems out of the ordinary. Your credit report will often contain numbers to the reporting financial company, so call them if you have any questions. - I monitor my online account activity on a weekly basis. Credit cards, banks, investment, etc. I try not to let anything slip. - Don't submit your financial or personal information to any sites linked from emails if at all possible. - Discard personal information securely. Shred, burn, destroy all personal information. I've debated just throwing things away, and I admit, I do sometimes. When I get lazy, I'll rip a credit application in about 6 pieces and throw some of it in one trash can and the rest in another. - Call my financial institution whenever there's a question mark. Should I find something suspicious, I would immediately track down exactly when and where that happened, and then take the appropriate steps to stop it. Here are some quotes taken from an article on msnbc.com:
Study results indicate that consumers who spot fraud online suffer an average theft of about $500. Consumers who wait for paper records and suffer ID theft suffer average losses of $4,500.
So monitor your credit card and online account statements! So your ID is stolen...now what?
Also promising, she said, was a result showing average consumer time spent dealing with personal records cleanup from ID theft is now 28 hours, down from 33 last year.
Do you have 28 hours, which probably doesn't account for everything, to talk to someone over the phone explaining to them that you are, well, you? Remember,
"The fact is that nobody is more effective at preventing and protecting fraud than the individual," he said.
Here are some references in case ID Theft strikes you: http://www.consumer.gov/idtheft/ http://www.complaints.com/directory/2004/april/18/11.htm http://www.msnbc.msn.com/id/6866768/ http://www.ssa.gov/oig/hotline/when.htm http://www.usdoj.gov/criminal/fraud/idtheft.html http://www.ftc.gov/bcp/conline/pubs/credit/idtheft.htm And you may be interested in Credit Monitoring services. Also, check out this post by Frugal @ My 1st Million At 33.